

Signup To Our Weekly e-News
"*" indicates required fields
We’ll never share your details with any third party in line with our privacy policy.
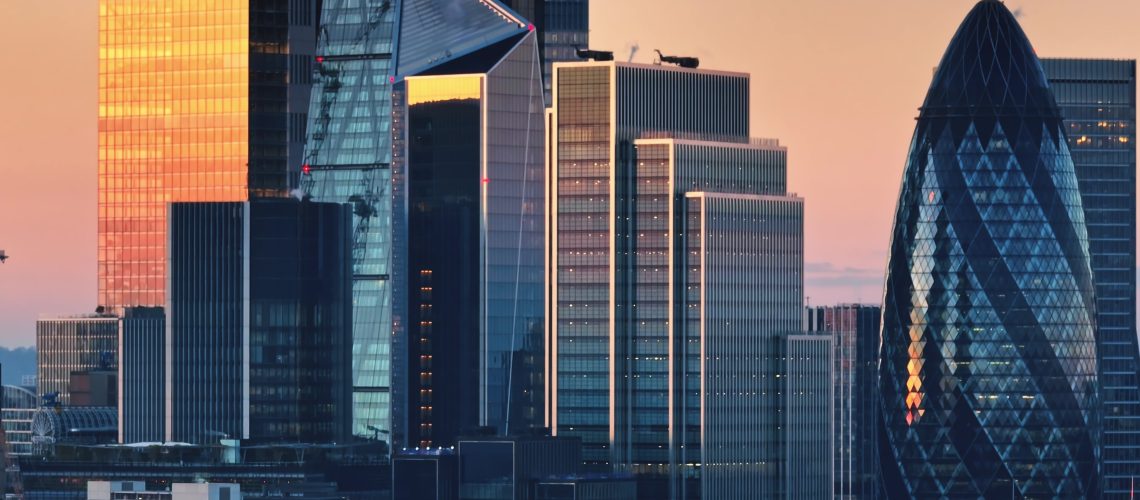
London’s office market is demonstrating clear signs of recovery, with momentum building across leasing, investment and redevelopment activity.
However, the market is not simply rebounding to its old ways. Instead, it is entering a more strategic phase, defined by a growing emphasis on quality, sustainability and long-term asset performance.
This shift is already evident in the leasing market. In Central London, take-up reached approximately 3.2 million sq ft in Q2 2025, marking the strongest second-quarter performance in ten years, according to JLL’s Central London Office Market Dynamics report. Demand is increasingly focused on high-specification office space that reflects evolving modern workplace expectations.
At the same time, occupiers are placing greater importance on assets with strong ESG credentials, flexible layouts and high-quality amenities that support employee wellbeing and productivity. As a result, leasing negotiations are becoming more nuanced, with increased attention given to building performance, energy efficiency and the adaptability of space to meet changing operational requirements.
In this context, this piece explores the key developments underpinning current market momentum, including shifts in occupier demand, trends in investment activity and the growing importance of sustainability and long-term asset performance.
Investment activity has also increased, with around £4.5 billion transacted in the first half of 2025, compared to £2.8 billion during the same period in 2024 as stated by JLL. Notably, larger lot sizes are re-emerging, with a growing number of high-value transactions progressing through the market. Data from CoStar indicates that the volume of £100 million-plus deals currently under offer is approaching the total deal volumes recorded across the previous year.
Despite this increase in activity, investor demand remains highly selective. Capital is being directed towards core, well-located assets with strong underlying fundamentals and the capacity to deliver long-term resilience.
Recent transactions reflect this trend. For example, the reported sale of Capital House by Barings to Daibiru for £169 million, illustrates continued appetite for buildings that combine ESG performance with digital infrastructure.
At the top end of the market, supply constraints are placing upward pressure on rents.
High-quality office space is achieving record rents, with recent deals such as the leasing at 8 Bishopsgate reportedly reaching £147 per sq ft as reported by Bisnow.
This trend reflects a broader repricing of office space, where value is increasingly linked to performance. Buildings that meet high environmental and operational standards are commanding significant premiums, while secondary assets are facing reduced demand and downward pressure on values.
Refurbishment activity has become central to asset management strategies, particularly as landlords respond to tightening ESG regulations and evolving occupier expectations.
Landlords are increasingly focusing on retrofitting and upgrading existing buildings to meet regulatory requirements and occupier expectations- rather than pursuing new development. This has become a central strategy for landlords seeking to future-proof assets and align with tightening regulatory requirements.
This approach is being supported by green financing initiatives. For example, Aviva Investors has recently provided funding to support the refurbishment of a West End office, illustrating the role of ESG-led capital in driving asset management.
In contrast, where refurbishment is not viable, some assets are being repositioned through alternative use strategies, including conversion to hotel or mixed-use schemes, as seen in recent acquisitions by investors such as Firethorn.
As a result of the trends just mentioned, a clear divide is emerging within the London office market: high-performing, sustainable assets continue to attract strong occupier and investor demand, while secondary stock faces mounting pressure to remain competitive.
This growing divergence is driving more active asset management, requiring landlords and investors to assess their portfolios carefully and make strategic decisions on whether to invest in refurbishment, reposition assets for alternative uses, or consider disposal.
London’s office market is moving beyond recovery and into a phase defined by strategic repositioning. Leasing, investment and development decisions are increasingly shaped by long-term considerations, particularly sustainability, quality and adaptability.
For occupiers, this means less choice and therefore increasing rents at the top end of the market, alongside growing expectations around building performance. For landlords and investors, the challenge lies in ensuring that assets remain competitive as expectations evolve.
Assets that meet the expectations are likely to see sustained demand and pricing strength, while others may require significant capital investment or fundamental repositioning to remain viable.
Our Commercial Real Estate team, led by Artan Llabjani, supports landlords, investors and occupiers in navigating London’s evolving office market. From lease negotiations and investment transactions to refurbishment projects and ESG compliance, we provide clear, strategic advice to help you maximise value, manage risk and keep your assets competitive.
Trusts can be an excellent tool for family wealth and estate planning. However, in divorce and financial remedy proceedings, they...
Buying a home is one of the biggest financial decisions most people will ever make. While it’s easy to fall...
"*" indicates required fields
We’ll never share your details with any third party in line with our privacy policy.